Imagine spending 35 years saving for retirement, finally opening your 401(k) statement and seeing $800,000.
You’ve done it. The mortgage is almost paid, the children are grown, and perhaps there’s finally time for that vacation you’ve been putting off.
The awkward question then arises. What is your real spending limit?
An $800,000 portfolio would yield around $2,600 per month in first-year withdrawals before taxes, using Morningstar’s 3.9% beginning withdrawal methodology.
Paychecks are not guaranteed. Social Security would be another source of income.
The difference might be shocking to someone used to making $80,000 a year.
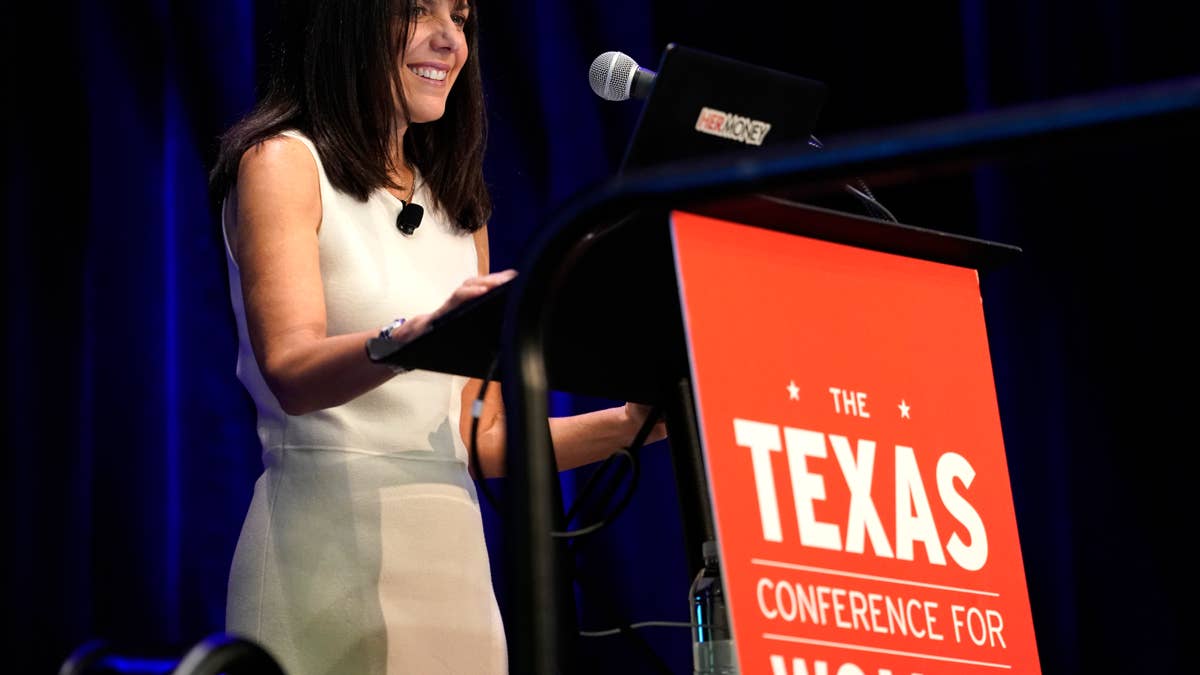
In a recent interview with Michelle Singletary of the Washington Post, personal financial expert Jean Chatzky reexamined the issue.
She addressed the well-known suggestion that Americans retire with 10 times their last yearly pay.
That equates to $800,000 for an income of $80,000. However, when the expenses come in, a retirement balance that seems huge on paper may feel much smaller.
Chatzky is aware of how depressing that computation may be.
Jean Chatzky understands why Americans feel overwhelmed
Fidelity Investments is the source of the 10-times-salary guideline, which suggests achieving that goal by the age of 67.
Fidelity suggests accumulating three times your salary by age 40, six times by 50, and eight times by 60.
The formula assumes workers start saving at 25, contribute 15% of their income, including employer contributions, and maintain substantial stock exposure.
That seems simple, but real life gets in the way. Years of meticulous preparation may be derailed by a divorce, a sick parent, a child’s college expenses, or a layoff.
Chatzky acknowledged the resistance, saying, “The internet does not like that number,” according to the Post.
However, Chatzky’s personal socioeconomic upbringing was far from spectacular. When she began her journalism career in 1986, she remembered making just $11,000 a year. At first, her costs exceeded her income.
Chatzky eventually changed her spending habits and now encourages workers to automate even modest retirement contributions, the Post noted.
Her argument was not that anybody can sock away a million dollars with ease. It’s that a daunting goal shouldn’t be used as a justification for not saving any money.
Jean Chatzky raises a question $1 million can’t settle.Marla Aufmuth / Getty Images
The retirement paycheck tells a different story
Consider two hypothetical retirees.
One continues to make mortgage payments despite having an $800,000 retirement account. The other owns a house outright and has a $600,000 account.
On paper, the first individual appears to be wealthy. However, the second may have fewer money worries each month.
The first retiree would receive $2,600 in monthly withdrawals under Morningstar’s 3.9% structure, while the second would receive $1,950. That’s a difference of $650.
Let’s say the first retiree has a $1,500 home payment and the second has none. The smaller portfolio no longer seems so insufficient.
Property taxes, upkeep, medical costs, and other responsibilities are still important, of course.
Social Security also modifies the financial picture. The Social Security Administration reported an average retired-worker benefit of approximately $2,089 per month in September 2026.
When you combine the example $2,600 withdrawal with the national average, you get around $4,689 per month before taxes.
That is around 70% of an annual income of $80,000; however, a person’s actual Social Security payment may vary somewhat.
More Retirement:
20 million Medicare beneficiaries may get a one-time $90 payment
Vanguard spotlights Roth IRA trap hiding in your income
Dave Ramsey raises a $185K risk Fidelity pegs for retirees
The figures clarify how two individuals with similar portfolios might retire in very different ways.
Even for a person with a larger retirement nest egg, worry might still exist. In her Nov. 3 column for the Post, Singletary described a 64-year-old woman who had saved more than $1 million.
Before her scheduled retirement date, she had been laid off. She was worried that her funds might run out and was already making withdrawals from her retirement account. Singletary recalled that the woman became emotional while discussing her finances.
The woman’s story shows why a seven-figure balance does not guarantee freedom from financial stress.
The $325 retirement calculation worth remembering
Consider a figure that adds a personal touch to retirement planning: An extra $100,000 in savings supports about $325 more in first monthly withdrawals at Morningstar’s 3.9% starting withdrawal rate.
That’s real money. It might pay for a portion of an electric bill, groceries, or auto insurance. However, it also shows how much Americans need to save to cover even small expenses.
Under the same assumptions, $100,000 in portfolio savings is needed to cover a recurrent $325 monthly cost.
This does not imply that eliminating a $325 spend would result in $100,000. It indicates that the size of a sufficient retirement portfolio is determined by spending requirements.
Morningstar’s framework assumes a 30-year retirement and a 90% probability of success under its modeled conditions. Its estimates aren’t guarantees.
For those who feel discouraged by million-dollar ambitions, Chatzky’s message provides some perspective.
Start with what you can afford. Recognize the potential costs of retirement. And keep in mind that, although not everyone can decide when to retire, working longer, cutting costs, or modifying expectations might alter the computation.
Whether your statement displays $800,000 or $1 million is not the most important retirement issue.
It’s whether you can afford the life you really want with that money, Social Security, and other sources of income.
Related: Suze Orman has a serious retirement warning for 2027