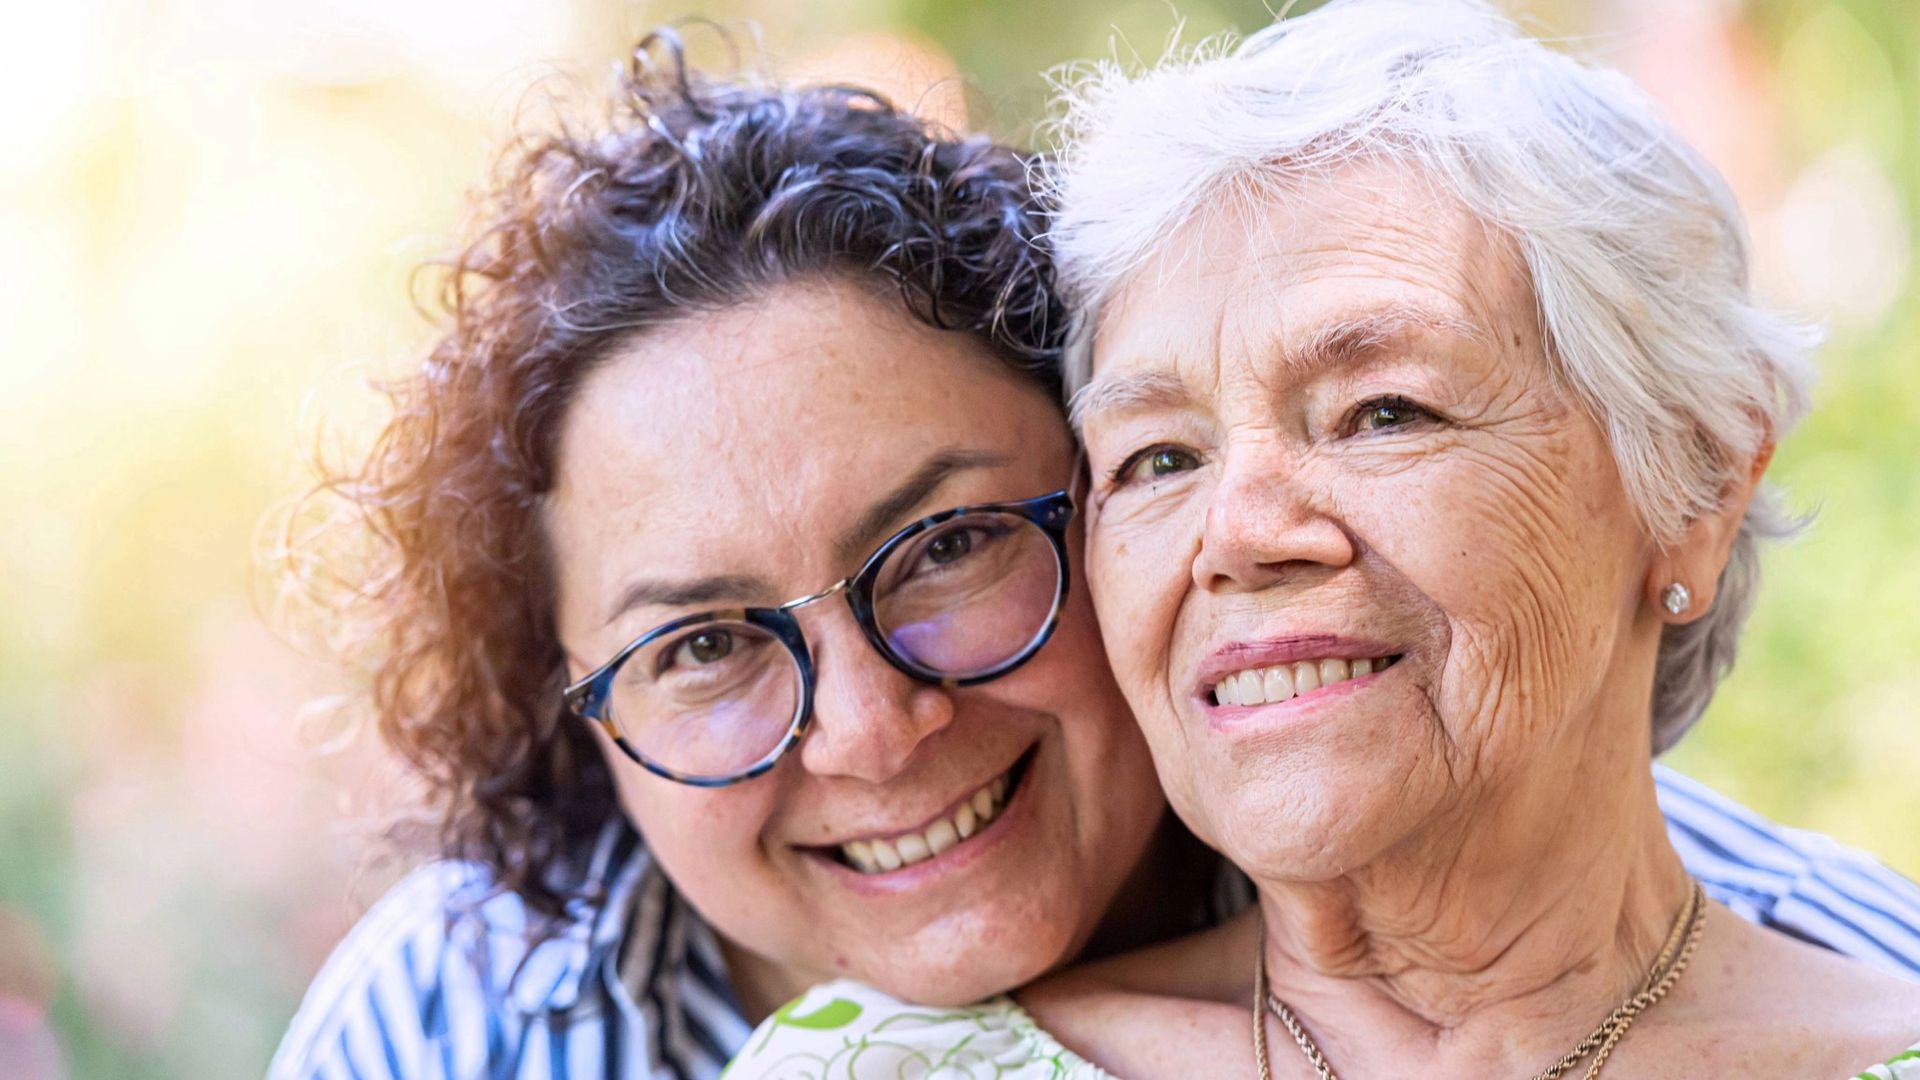
Editor’s note: This article is the second in a three-part series on the benefits of taking a more thoughtful and proactive approach to financial planning. Part one is Protecting Family Wealth Means Allowing Your Kids to Get Involved — and Letting Them Make Some Mistakes. Here’s Why. In the first article of this series, I wrote about a quiet transition moment that happens as children move from financial dependence toward financial awareness and responsibility. The next quiet transition moment is in the opposite direction, when we recognize that our aging parents may one day need help managing the lives they have spent decades building.There is rarely a single moment when this shift begins. Your parents may be retired but still independent and active — traveling, volunteering and enjoying life. Nothing appears to require immediate attention, yet this is the best time to start planning.As a member of the “sandwich generation,” I know that caring for aging parents while juggling your own family’s needs and your career can be challenging. You’ll need to have the right legal structures and documents in place, as well as an understanding of available resources. But the first step is to create continuity without making parents feel that their independence is being questioned or taken away.About Adviser IntelThe author of this article is a participant in Kiplinger’s Adviser Intel program, a curated network of trusted financial professionals who share expert insights on wealth building and preservation. Contributors, including fiduciary financial planners, wealth managers, CEOs and attorneys, provide actionable advice about retirement planning, estate planning, tax strategies and more. Experts are invited to contribute and do not pay to be included, so you can trust their advice is honest and valuable.Start with permission, not an account statementAdult children often approach this conversation by asking for information: Where are the accounts? What are the balances? Is there a power of attorney? Those are important questions, but they may not be the best place to begin.To a parent who has managed the family finances for decades, a request for information can sound like a request for control and signal distrust. The child intends to help, but the parent may hear, “You can no longer handle this.”A better opening is to ask what the parent wants for themselves. For example, ask your parents: If you ever needed help, who would you want to be involved? What would you want that person to know? What would make it easier for someone to carry out your wishes without disrupting your life?This reframes the conversation around preserving independence. Good planning helps a parent remain in control for as long as possible and ensures that, if help is needed, it arrives on the parent’s terms.Build a roadmap, not a balance sheetAdult children don’t necessarily need to know their parents’ net worth or see every account balance. Instead, what’s important is how to find the right information when the time comes.That roadmap might identify: Financial institutions and insurance policiesDebts and recurring obligationsTrusted advisersThe location of important recordsIt should also address digital access. Increasingly, the missing information is a password, an authentication device or an online account that no one else knows exists.Imagine trying to reconstruct a parent’s financial life from a hospital waiting room. That is not the moment to learn that no one knows where the original documents are stored or whom to call about an investment account.A plan should be reviewed periodically because advisers change, accounts move and instructions become outdated. A plan that can’t be found or followed isn’t much of a plan.Make sure authority matches responsibilityInformation alone doesn’t give someone the legal authority to act. A parent may say, “If anything happens, you know what to do,” but good intentions don’t grant access to an account or the legal ability to make a decision.Powers of attorney, healthcare directives and estate documents should be addressed while parents have the capacity and time to make thoughtful choices. The rules vary by state, so families should work with qualified legal counsel.The conversation should go beyond signing documents. Does the appointee understand the role? Is the document structured to work when needed? Do relevant family members know whom the parent selected and why?In my experience, the “why” matters the most. For example, if one sibling is selected and another isn’t, the decision can be misread as a judgment about love, trust or competence. Meanwhile, the child who is selected may not even want the responsibility or have the time or expertise to fulfill it. Responsibilities can also be divided, or an independent professional or institution may be appropriate. The desire to treat children equally does not always require identical roles. The key is communication because, as we all know, people tend to fill unexplained differences with their own stories.Create a succession plan for the familyBusiness owners understand that an organization shouldn’t depend indefinitely on one person holding all the knowledge. Families should apply the same principle to their own financial lives.In many households, one spouse manages investments, the other pays household expenses, and only one knows the advisers. That system may work for decades. The vulnerability becomes clear when the person holding that knowledge can no longer manage it.Ask yourself a simple question: Who is the backup?The answer doesn’t require an immediate handoff. An adult child might join an annual meeting with the parents’ adviser. A spouse who hasn’t managed the investments might receive a plain-language overview. A trusted person might know where the roadmap is stored without having access to use it today.As in business succession, the objective isn’t to push out the current leader. It’s to protect what that leader built and make an eventual transition less disruptive.Looking for expert tips to grow and preserve your wealth? Sign up for Adviser Intel, our free, twice-weekly newsletter.Plan for life, not only for deathEstate planning often focuses on what happens after death. Aging raises equally important questions about the years before it.Where would your parents want to live if maintaining their home became difficult?Would they prefer help at home, a move closer to family or a community with increasing levels of care?Who will coordinate appointments, finances and caregivers?What resources are available?How might care affect both the parents and their children?These are not only financial questions; they also involve housing, health, time, dignity and family relationships. Money creates choices, so the conversation should begin with the life the parents want to preserve. Only then can the family determine whether the legal and financial plan supports it.Life doesn’t unfold as a neat sequence of transactions. Parents may remain independent for many years, or circumstances may change suddenly. The objective is not to predict the precise moment when help will be needed but rather create enough clarity and continuity that the family can adapt when it is.If your parents are healthy and managing everything well, this conversation can understandably feel premature. Yet, in many ways, that is exactly the point.In the final article of this series, I will turn to another kind of quiet planning moment: The major life events that never happen. This includes a long-term partnership without marriage, a business that never got sold, and caring for loved ones falling outside the traditional definitions of family.Related ContentHow to Talk to Your Parents About Money Without OversteppingHow to Talk About Touchy Subjects With Loved Ones, Before a Crisis Turns ‘Ifs’ Into RealityHow to Tackle Digital Estate Planning in Four Easy StepsCaring for Aging Parents Takes Planning Ahead and PatienceCome as You Are: Wealth Management for Gen XThe information provided is for illustrative/educational purposes only and is not intended to constitute legal, tax, investment, or financial advice. The information discussed herein may not be applicable to or appropriate for every investor and should be used only after consultation with professionals who have reviewed your specific situation. BNY Wealth conducts business through various operating subsidiaries of The Bank of New York Mellon Corporation.This article was written by and presents the views of our contributing adviser, not the Kiplinger editorial staff. You can check adviser records with the SEC or with FINRA.