The AI data center boom is not cooling off, even if the buildings themselves badly need to. Microsoft and Oracle are sitting on huge contract backlogs, and the only way to turn those promises into revenue is to build more capacity, fast. That rush is also lifting suppliers like Vertiv Holdings, which sells the cooling and power gear every new facility needs.
The money involved keeps getting bigger. Goldman Sachs expects the five largest U.S. hyperscalers to lift AI infrastructure spending to $1.2 trillion in 2027 from about $800 billion this year. The bank also estimates these companies need about $300 billion in yearly AI revenue just to break even.
Microsoft’s backlog keeps growing
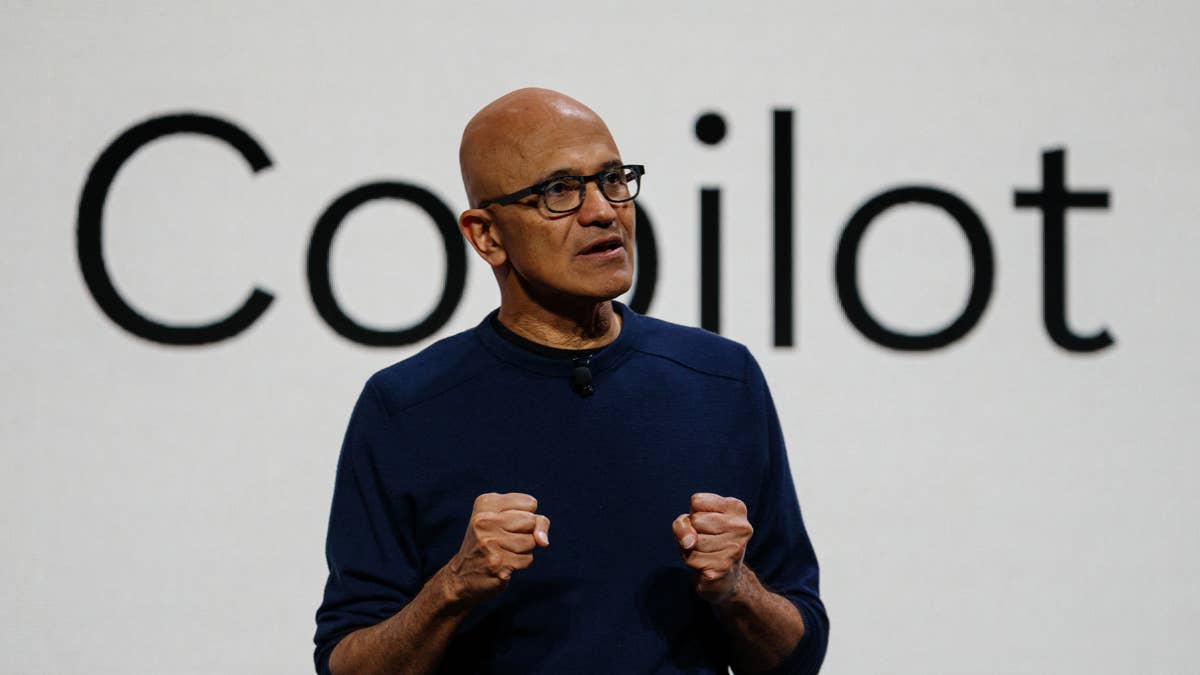
Microsoft has more signed business than it can serve today. Its commercial remaining performance obligation, which tracks contracted revenue not yet recognized, jumped 73% to $677 billion in the quarter ended September 30, while Microsoft Cloud revenue climbed 30% to $63.9 billion. “We are delivering greater capability, choice, control, and cost efficiency for customers across our entire stack,” CEO Satya Nadella said.
Also read: Microsoft just gave Nvidia shareholders a reason to pay attention
The quarter itself beat expectations. Revenue rose 19% to $92.3 billion, and Azure grew 48%, ahead of the roughly 45% Wall Street had expected. CFO Amy Hood defended the heavy spending, saying “each dollar of CapEx has the potential to support more revenue and higher returns over time.”
The spending bill is rising quickly. Microsoft put $45.2 billion into capital projects in the quarter, with about three-quarters going to short-lived assets such as GPUs, CPUs and networking gear. Hood expects capex to top $50 billion in the second quarter, with Azure growth guided to 49% to 50%. She said, “We still have demand that exceeds supply.”
Microsoft also has room to keep paying for it. The company uses leasing and debt markets as part of its funding mix and expects to stay free cash flow positive in fiscal 2027. Nadella added that Microsoft will sell capacity when the pricing is right.
Oracle’s backlog also goes all in
Oracle’s backlog is nearly as large. The company reported remaining performance obligations of $664 billion in its fiscal first quarter, up $209 billion from a year earlier. Total revenue rose 30% to $19.3 billion, while cloud infrastructure revenue more than doubled to $7.4 billion, according to Oracle.
“Customer demand for AI Cloud Training and Inferencing Services continues to grow faster than supply,” Oracle said. It booked more than $30 billion in new AI cloud contracts in the quarter and expects about half of its backlog to turn into revenue over the next 36 months. Management raised its full-year revenue guidance to at least $90 billion and called fiscal 2028 its peak spending year.
Paying for that build-out is the hard part. On November 2, Oracle filed to raise $10 billion in senior notes and another $10 billion in common stock. It expects free cash flow to turn positive in the second half of fiscal 2028. The shares fell that day, leaving them well below their September 2025 peak.
Oracle is getting creative too. It is using a $35 billion AI purpose vehicle with Apollo and Blackstone to keep some deployments off its balance sheet. At the same time, a force majeure notice has delayed payments on its Project Jupiter data center in New Mexico.
Goldman Sachs data also shows AI-related issuers paying about 115 basis points on new debt, compared with 78 for the broader investment-grade market, TheStreet reported.
The AI data center boom is not cooling off, even if the buildings themselves badly need to.Justin Sullivan / Getty Images
The cooling bottleneck lifts Vertiv
All that new capacity creates a heat problem. Standard data center racks run at about 10 to 20 kilowatts, while racks built around Nvidia’s Blackwell chips can need 100 kilowatts or more, pushing operators toward liquid cooling.
The market for fixing that problem is growing fast. The global data center cooling market was worth about $18 billion last year and is forecast to reach roughly $141 billion by 2036. AI servers, denser racks and a move toward direct-to-chip and immersion cooling are behind that growth, according to Research and Markets.
Vertiv is riding that wave. The company sells power, thermal management and liquid cooling gear, and its third-quarter revenue jumped 61% to about $4.31 billion. Adjusted earnings came in at $2.21 a share, and organic orders more than doubled from a year earlier.
More Microsoft:
Microsoft’s $665 target hinges on a new AI advantage
Meta and Microsoft just sent employees a memo about Anthropic
Microsoft just sent a strong message to Anthropic
The company also raised its full-year outlook. Vertiv now expects 2026 revenue of $14.65 billion, up $650 million from its July forecast, and adjusted earnings of $7.15 a share. It plans to double its chiller production capacity by year-end to keep up with orders.
What this means for Microsoft and Oracle investors
Wall Street is rewarding Microsoft for now. Its shares rose more than 5% after hours following the October 28 results, even as Alphabet fell about 10%. Capital.com analyst Daniela Hathorn said the two reports offered “competing narratives” on whether AI is paying off, as reported by TheStreet.
Microsoft investors still need to watch where that backlog comes from. In January, Hood said about 45% of the company’s remaining commercial performance obligation came from OpenAI. Goldman Sachs analyst Gabriela Borges, who rates the stock a Buy, lists weaker-than-expected OpenAI revenue as a key risk.
Oracle investors face a longer wait for the payoff. The company targets more than $225 billion in revenue and adjusted earnings above $21 a share by fiscal 2030, but Scotiabank and Wells Fargo both trimmed their price targets in late October. Oracle’s next test comes when it reports fiscal second-quarter results on December 14.
Related: Jim Cramer sends strong signal to Oracle stock investors