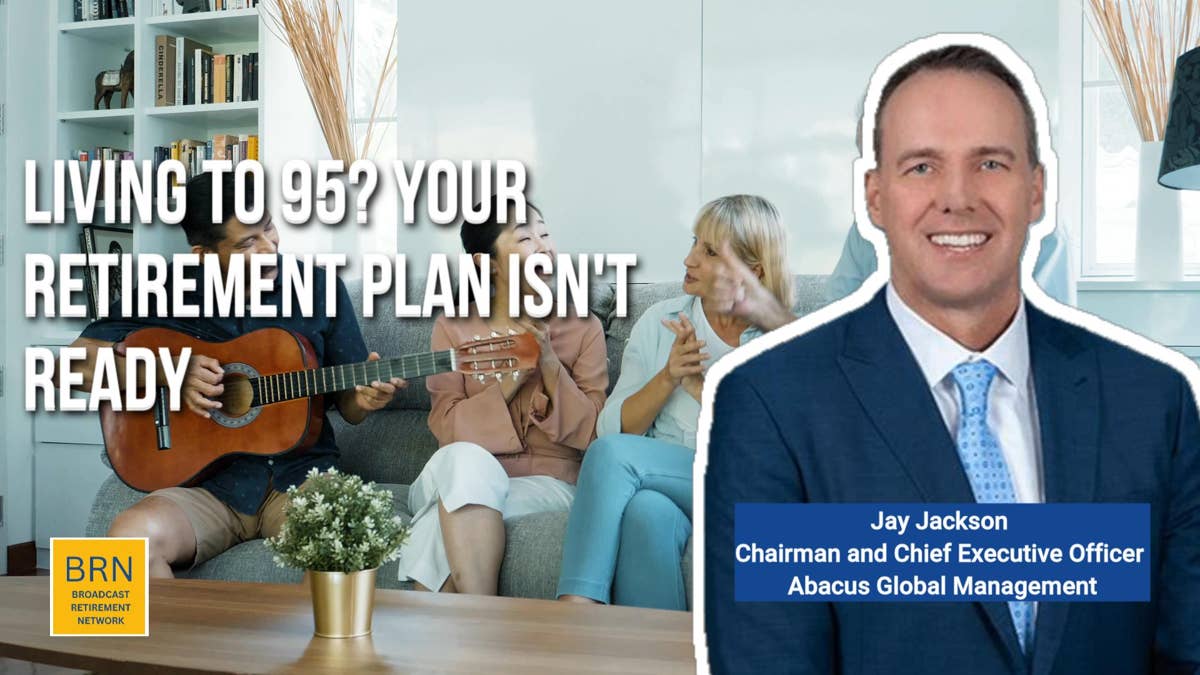
In this episode of the Broadcast Retirement Network, Jay Jackson, Chairman and CEO of Abacus Global Management, explains why living longer has become one of the biggest challenges in retirement planning.
Transcript:
Jeffrey Snyder, Broadcast Retirement Network
Well, Jay, it’s so great to see you. Thanks for joining us in the program this morning.
Jay Jackson, Chairman and CEO of Abacus Global Management
Awesome, yeah, super excited to be here.
Jeffrey Snyder, Broadcast Retirement Network
Well, we’re excited to have you and I really appreciate you. I know how busy you are at Abacus, so we appreciate you coming on. You recently wrote a really thoughtful piece on longevity, and it’s no surprise to any of us that watching the show, or probably to you, that we’re living longer.
And longevity is a good thing. I’m happy to live as long as I can, as long as it’s a healthy, health span is good. But this also presents a financial challenge.
Jay Jackson, Chairman and CEO of Abacus Global Management
It sure does, and it’s one of the things that we’ve decided to try to address head on. The facts are this, is that yes, we are living longer, but what’s really happening as well is that you’ve got this massive wealth transfer that’s eventually going to occur too. And when we think about the wealth transfer, we think about longevity and living longer, how is someone’s financial plan capturing that?
If we assume most people are going to retire at age 65, you’re familiar with this, Jeff, is that you’ve got target date funds for 401ks. What do you have in retirement? Now you can argue annuities, you can say some of these other things, but you’re really limiting your upside.
Understanding how long you’re going to be in retirement, we don’t really call it lifespan as much as we call it someone’s life arc because it’s an arc of probabilities, will have a fundamental difference in how you allocate when you retire. We think people go conservative far too early, they should be investing more aggressively when they’re 65, not going into fixed income day one.
Jeffrey Snyder, Broadcast Retirement Network
So let me ask you about age 65, because do you think that’s kind of the old way of thinking? Look, I think 65, I’m closer to that than I am to 25. I got to tell you, I think 65 is the new 20.
So I mean, are people really thinking about retiring at 65 or do you think they’re thinking about working longer or doing something different?
Jay Jackson, Chairman and CEO of Abacus Global Management
You touch on something so important, but if you bring it up to somebody who’s 65 and says, don’t retire, it becomes, right? It becomes this, no, no, I have earned my right here. It’s the same thing with social security.
There’s a big debate as to whether people think they should defer or not. What I always say is before you make that decision, better understand your lifespan. What Abacus does is that we have aggregated over 20 years of medical data and resulting mortality data so that people can have a clear understanding of what their forecasted lifespan might look like, i.e. their life arc to ensure they don’t run out of money. But if they understand that, if you’re 65 with a 15 year lifespan, you should not defer social security, right? And that’s gonna be based on your current health conditions, your family history, your genetics, where you live, all those things weigh in. The challenge is no one’s even asking that question.
That’s what’s crazy. We should take a second and understand that the most important piece of data we’re gonna face when we retire is how long you’re going to be there. And what we’re trying to address head on is capitalize on all the data we have and then utilize these tools so that people can make better, smarter decisions and improve their outcomes.
Social security is looking to draw a negative somewhere in 2030, 2032. Those are the numbers we’ve heard. If a larger percent of the population better understood how long they were going to be in retirement, a large part of the population would probably defer and wouldn’t step into retirement.
Let’s call it the biggest impact to longevity and increased life, lifespan, healthspan, all those things is remaining working.
Jeffrey Snyder, Broadcast Retirement Network
Yeah, I think, look, I’m right there with you. And I don’t mean this to be an indictment on the retirement industry, because that’s not my intent. But don’t you think some of the, and I understand the rationale because I’ve been in the business for 30 years.
You’ve been doing it for a long time. But don’t we need to rethink the 4% withdrawal rule and some of these other things that, I think they made sense in a world where people lived shorter lifespans. But also we live in a world, Jay, where we’re talking about personalization.
You’re different, Jeff Snyder’s different, my wife’s different, we’re different. We need personalization.
Jay Jackson, Chairman and CEO of Abacus Global Management
Every single person is different, you’re not averages. And what happens is that 4% was derived from the average. So the average US lifespan is 78 years old.
However, you have a 50% probability once you live to 65 to living to age 90 now. So that is 4%, it’s 100% broken. I think that if you’re just going to be 65 and step into annuity, think about what you’re giving up.
If you had $2 million walking into retirement, that’s what, 100 grand a year? Certainly maybe for the rest of your life. And if you’re going to live there 15 years, we’ll see.
But you should be drawing 200 grand a year. Staying in equities, right? Staying in alts.
Don’t give up some of your ability to withstand risk because you’ve got 20, 24 years left. If you have a 21 year lifespan, that’s three doubles on $2 million. That means your two can grow to 16.
By the time you take out withdrawals, you could be having $10 million instead of either zero at the end of the annuity or being in a fixed income instrument where you just have 2 million. So this is a massive, massive impact. The challenge is nobody really had this conversation.
We all kind of knew it underneath and now you can get an instant output to help you do that. I think the secret to this too is you’re dealing with fear. When you start to talk about people’s number, right?
A lot of people get scared. They say to themselves, I don’t want to know. It’s like saying, I don’t want to get an MRI test because I don’t want to know I have stage one cancer.
Well, it’s better in stage four, but let’s make people greedy. If I can double your retirement income, would you like to know now? Of course I would.
I would. Makes perfect sense. Let’s get your meds.
Let’s get these things going. And so that’s what we’re kind of working through right now. And we’re putting this information out to everybody.
It’s going to fundamentally shift how people allocate in retirement. 4% is broken. Every financial advisor knows it.
They just don’t have the tools to make the better decision for their clients.
Jeffrey Snyder, Broadcast Retirement Network
I read recently, Jay, that retirees in particular are very reticent to spend their money. And I think that was from another organization that put that research out. But it really is telling that given all these things we know, the extended lifespans, you didn’t save money just to pass it on.
I mean, maybe some people did. And I have nieces and nephews that I’ll probably pass on money to. Please, hopefully they’re not listening to this right now.
But in all seriousness, why do you think that is that people are so reticent to spend their hard-earned retirement dollars?
Jay Jackson, Chairman and CEO of Abacus Global Management
It is an absolute fear of running out of money. It’s the number one fear. It’s next to death, is that they don’t want to run out of money.
They don’t want to move back in with their kids. And the fear is driven by the fact that they don’t have the data to make the decision. If they have the data, then they wouldn’t have that fear.
We actually show people to say, hey, this is your expected lifespan. Now look, there’s a probabilistic outcome that could change here. But the other things that we do is we re-underwrite them every year.
How do you address the fear? Well, Jay, what if things change? Great, no problem.
Let’s re-underwrite you every single year and make those adjustments based upon your current health profile. It might be longer, it might be shorter, so that your fear is duly acknowledged, right? And not thrown into the average.
This is a crazy stat that I think everybody should pay attention to. I went in and got my own financial plan. I won’t say who it’s with, but it’s a really large bank.
And they ran it to age 95. Now I’m six five. Have yet to find another human who’s lived in age 95 at six five.
It’s very rare. Honestly, height has a huge impact. Like there’s very few centurions ever over six foot tall.
Dick Van Dyke is one of them now. Very rare. Yet you’re gonna tell me I have this probability and you’re planning to age 95?
That’s broken. That’s just absolutely not based on fact, right? And that’s because they have a fear that says, well, geez, Jay, I’m gonna go this ultra conservative route.
The ultra conservative route is you actually get the data and make the right decision. And that’s what people are starting to do now because it’s gonna literally double their retirement income, maybe triple some of their outputs when it’s regards to how much they’re gonna leave. 120 trillion in a wealth transfer, you allocate appropriately, it’s 150 trillion.
Jeffrey Snyder, Broadcast Retirement Network
Let me ask you about annuities because you mentioned that earlier. You can’t help but read, there’s a big push among the insurance providers. And again, I’m not indicting anyone.
I can understand you’re in business to make money. I totally, for your shareholders and for yourself, totally respect that. But are annuities appropriate for everybody?
And should they be, if they are appropriate, should they be inside the retirement plan, which is what is being discussed? Or should it just be like, hey, I’m just gonna roll, instead of rolling to an IRA, I’m gonna roll a portion of my balance to an annuity. So does it still fit into that withdrawal equation?
Jay Jackson, Chairman and CEO of Abacus Global Management
Well, as we all know, everyone’s different. And I think that there are scenarios where there’s no chance someone should go to an annuity day one, particularly somebody who’s ultra healthy, right? You’re just, if you’ve got a very high probability to living past age 85 and you’re 65 and you have 20 plus years, you should remain allocated.
The way that I think about it is this, Warren Buffett made 98% of his wealth past age 65 because he understood the power of compounding. That’s what you’re taking away from yourself if you just give all your assets over too early. I think an annuity can make sense as maybe a portion of your portfolio on a go forward basis, but that’s not your retirement.
That’s not your self-funded pension the way that they’re advertised today. If you have the data, why would you give up all the upside? You wouldn’t do it on your home.
You wouldn’t do it in any other asset that you own to say, oh, I’m just gonna give this over to you and not have any upside for the security of having the income. People do that because they don’t know how long they’re gonna be in retirement. They have this fear of running out of money.
Give them the data and then what’ll happen is like, yeah, it makes sense for maybe a small part of what I do, but overall I should remain allocated. And I think that’s the biggest message people should take. With information, you’re no longer limited based upon the asset allocation and the success you’ll have in retirement.
There’s no reason to put money in your mattress anymore. If you have it, you should spend it. It’ll cover your medical costs.
Our program actually factors all of that in.
Jeffrey Snyder, Broadcast Retirement Network
Let me ask you about the role of long-term planning because this is something we did a show recently on the fact that there are not enough senior living centers or beds, I guess, nursing home beds for people. The cost of long-term care is exorbitant. And I think another financial firm even said that as you get older, the cost of healthcare, and that is the last five to 10 years are gonna be through the roof.
So how do you factor in long-term care into what we’re talking about this morning?
Jay Jackson, Chairman and CEO of Abacus Global Management
Sure, when you look at someone’s life arc, one of the things you need to do is actually look at their updated medical profile. Like I said, what we do is we go and retrieve all their medical files, look at their family history. If they have a family history of let’s say, early onset dementia and Alzheimer’s, and you have a genetic profile to meet that, you wanna factor that into that arc of planning to where memory care can cost as much as 15 to $20,000 a month when somebody reaches a certain age.
And understanding when that comes in is how you should be allocating to compensate for that. So in our model, we actually get to, particularly past age 83, 84, if somebody has a potential for Alzheimer’s, we wanna factor that into that plan along with, you know what else it means? That if you just put it into 5% earning products, you’re not gonna have enough and you’re gonna start dipping into your capital accounts.
It’s why you should be allocated into equities, into alts, into things that produce better yields than just giving that money away and all your upside away so you could factor in that increased cost related to your medical, but you may not have that risk. And if you don’t have the risk, you don’t need to allocate as much for that, right? What’s really fascinating about people who live to 100, it’s not that they don’t get cancer, they just get it much later.
Jeffrey Snyder, Broadcast Retirement Network
Yeah.
Jay Jackson, Chairman and CEO of Abacus Global Management
And that’s the health span you’re talking about, right? We wanna show people not only how they can improve their financial incomes, but how can they improve their health outcomes? And we’re seeing this happen.
Jeffrey Snyder, Broadcast Retirement Network
Jay, I wanna ask you a question. It’s not necessarily on the subject matter, but I think it directly relates to that. And that is the role of artificial intelligence into what we’re talking about.
And also, how does it work? How are you seeing AI or super intelligence, depending on who you talk to, how are you seeing it in all seriousness? How’s it being incorporated into the world that you and I are in, retirement and financial planning?
Is it a big part, a small part? Is it getting bigger? How’s it working?
Jay Jackson, Chairman and CEO of Abacus Global Management
It’s getting bigger. And one of the things I think where AI is super helpful that no one will debate is that it will help improve health outcomes. There is a real positive trigger to artificial intelligence, super intelligence, however we frame it, to help improve health outcomes.
We know this. And that’s one of the things that unilaterally everybody thinks is gonna be a great outcome. If you’re improving your health outcomes, that should translate directly to your financial plan.
And that means that if you’re gonna live longer in your financial plan, how you allocate your financial plan is gonna be that much more important. And we capitalize on AI so we can translate those medical files instantly. What used to take days and weeks to retrieve and read someone’s medical files, we can now do in a minute.
What an amazing update, right? And now you give those medical information back to people and they can then start to make thoughtful decisions around their health and around their financial planning.
Jeffrey Snyder, Broadcast Retirement Network
Yeah, I mean, like you, I kind of see it not as a threat to the world that we’re in, I see it as a compliment. I think you’re always gonna need, I just think that the ability to relate to other people, to be empathetic, that is certainly a human quality. It’s not one that is not easily replicated, but I guess time will tell.
Jay, we’re gonna have to leave it there. It’s always great to see you. Thanks for joining us and we look forward to having you back on the program again.
Jay Jackson, Chairman and CEO of Abacus Global Management
Absolutely, can’t wait. Thank you so much.