Chevron Corporation (CVX) got another positive evaluation from Wall Street, and this one came with a higher price target.
HSBC raised its price target on the oil giant to $250 from $218 while keeping its Buy rating. The move was part of a wider set of changes the bank made to its oil ratings this week as crude prices stay high.
The timing is interesting for Chevron shareholders. The stock trades near $204 and is up more than 31% for the year, but it has fallen from its September peak of about $217.
At the new target, HSBC is basically saying the recent drop is a chance to buy more.
Inside HSBC’s $32 bump for Chevron
HSBC’s September 25 decision to raise its Chevron target by $32 was part of a broader shift in its oil ratings. The bank also upgraded BP and TotalEnergies to Buy while keeping Buy ratings on Shell and Repsol, according to Investing.com.
The analyst team pointed to the fact that Chevron’s profits go up quickly when oil prices rise. That is because the company focuses heavily on producing crude oil.
HSBC raised its cash flow forecasts for Chevron by 15% for 2026, 46% for 2027, and 23% for 2028, Investing.com reported.
More Oil Coverage
ETF fueled by Iran war goes bonkers, gains 3,600%
Chevron CEO sends a strong message on oil price and the economy
JPMorgan strongly recommends buying tumbling energy leader
At about $204 per share, the new $250 target means the stock could gain another 22% or so. If it gets there, Chevron would be well above its all-time high, rewarding shareholders who held on through this year’s sharp oil price swings.
HSBC also noted that Chevron has “the lowest” Middle East exposure of the five biggest global oil companies. With supply routes through the Strait of Hormuz still at risk, that gives Chevron a real advantage.
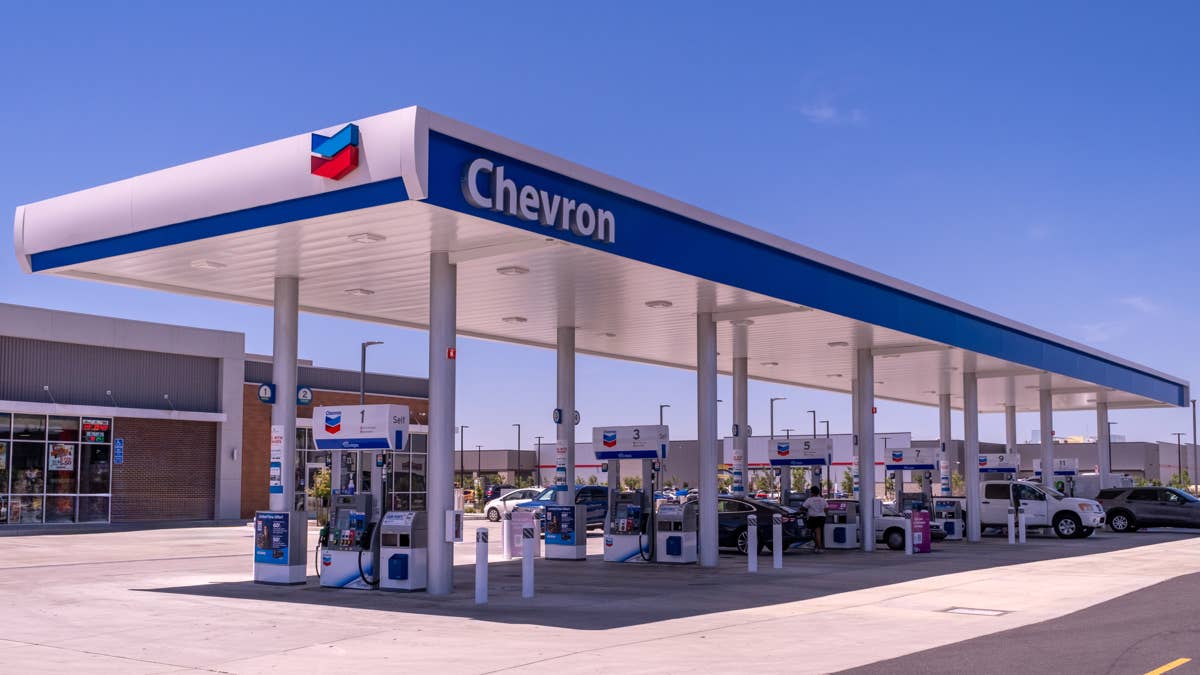
HSBC cites Chevron’s oil sensitivity and low Middle East exposure as reasons for a new price target.Juanmonino / Getty Images
What Chevron does and why oil price swings matter so much
Chevron is one of the largest oil and gas companies in the world. It pumps crude oil and natural gas out of the ground, moves it through pipelines and tankers, and turns it into gasoline, diesel, jet fuel, lubricants, and chemicals at its refineries. About 71% of its net sales came from refining and distribution at the end of 2025.
That matters because Chevron’s profits move with the price of oil more closely than most of its rivals. When Brent crude trades above $90 a barrel, Chevron’s profits climb fast. When it falls near $60, they shrink just as quickly.
Chevron’s second quarter results showed this pattern clearly. The company reported adjusted earnings of $12 billion, or $6.06 per share, beating expectations, according to Yahoo Finance.
Global production hit 4.07 million barrels of oil per day, up 20% from a year earlier, helped by the Hess acquisition and record U.S. output.
CEO Mike Wirth, who has led Chevron since 2018, said the results reflected “disciplined investment and strong execution.”
Bigger buybacks, 39 straight dividend hikes, and a Venezuela push
The clearest benefit of HSBC’s upgrade for shareholders is what the bank thinks Chevron will do with all that cash. HSBC now expects Chevron to raise its yearly buyback pace to $15 billion, up from a range of $10 billion to $12 billion.
Buybacks reduce the number of shares in the market. That helps push up earnings per share and, over time, the stock price. For long-term Chevron holders, each remaining share becomes a bigger claim on future profits.
The dividend record is even stronger. Chevron has raised its dividend for 39 years in a row, putting it in a small group known as Dividend Aristocrats.
The current quarterly dividend of $1.78 per share works out to a yield of about 3.48%, well above the average yield on the S&P 500.
The company is also growing overseas.
Wirth said Chevron’s $7 billion Venezuela push reflects “our confidence in the country’s deep resource potential.” He also told the University of Texas Energy Symposium that the expansion will be paid for with local profits.
What could possibly trip up the $250 target
No price target is a guarantee, and Chevron faces some risks that could keep the stock from reaching $250. The biggest risk is oil itself. HSBC’s higher cash flow forecasts rest on the idea that crude stays high due to ongoing tensions abroad.
If Middle East / Iran hostilities calm down and Iranian oil returns to global markets, the boost that war worries added to Chevron’s earnings could fade fast.
That already happened once this year. When the Strait of Hormuz reopened in late June, WTI crude fell to about $69 a barrel, and Chevron and Exxon shares both dropped sharply.
Chevron also has more to lose than several rivals if U.S. natural gas prices drop, since it has a bigger LNG footprint.
HSBC’s own note flagged that its lower 2027 gas price forecast hits Chevron harder than most peers. The stock is solid, but its profits still depend on a commodity nobody fully controls.
Related: Louis Navellier delivers hot take on rising bond yields