Bloom Energy (BE) shares plunged more than 11% on Friday, Oct. 23, despite the fuel-cell maker reporting better-than-expected third-quarter earnings and raising its full-year outlook.
The sell-off comes as investors grow increasingly sensitive to AI-related headlines. Meta Platforms (META) shares also fell this week following its latest earnings report, as concerns over the cost of massive AI investments overshadowed strong results.
Bloom Energy makes fuel-cell systems that supply electricity to data centers and semiconductor factories. The company joined the S&P 500 last month.
“What began with hyperscalers is rapidly moving across market segments because every business needs reliable power to grow,” Bloom Energy founder and CEO KR Sridhar said in a statement.
The stock has rallied 122% year-to-date, benefiting from surging AI demand. But now investors are questioning whether its rapid growth can justify its valuation.
Bloom Energy raises outlook but reports negative free cash flow
The company reported third-quarter adjusted earnings of 94 cents per share, well above analysts’ expectations of 69 cents. Earnings were also up sharply from 15 cents a share a year earlier.
Revenue jumped 138% year over year to $1.24 billion, beating Wall Street’s forecast of approximately $1.06 billion.
Also read: Meta stock falls despite Wall Street analysts raising price targets
Bloom also raised its full-year 2026 guidance, now expecting earnings of $3.10 to $3.40 per share on revenue of $4.4 billion to $4.6 billion.
Despite the rosy numbers above, Bloom reported more than $180 million in negative free cash flow in the third quarter.
“This quarter we used cash from operations. But that’s not the beginning of a trend,” Bloom’s CFO Simon Edwards explained on the earnings call. “We generated positive [cash flow from operating activities] year-to-date.”
“We really do believe that this business will be a free cash flow positive business as we think about continuing to be able to fund our own growth,” Edwards said.
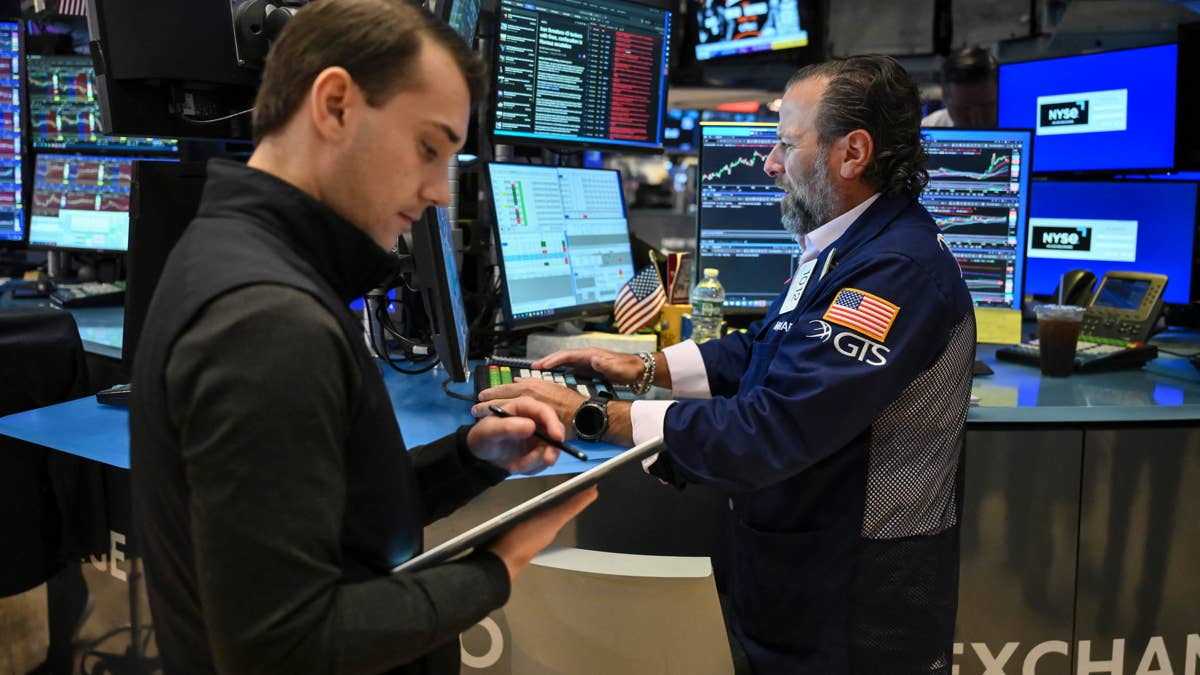
Bloom Energy stock is up 122% year-to-date.Michael M. Santiago / Getty Images
Wall Street analysts split on Bloom Energy stock targets
Wall Street analysts offered mixed reactions to Bloom’s latest results.
JPMorgan lowered its price target on Bloom Energy to $292 from $314 while maintaining an Overweight rating, according to The Fly.
The firm attributed the reduction to lower trading multiples among comparable companies rather than concerns about Bloom’s operating performance.
Related: CoreWeave stock plunges 12%, but Wall Street analyst says buy the dip
JPMorgan noted that Bloom’s third-quarter results were well above expectations and that the company had significantly raised its 2026 guidance for the third time this year.
The company’s execution “continues to impress,” JPMorgan said.
Morgan Stanley is more bullish on the stock for similar reasons. The analyst raised the price target on Bloom Energy to $335 from $310 while maintaining an Overweight rating.
The firm said Bloom exceeded both Wall Street consensus and buy-side expectations for revenue and EBITDA (earnings before interest, taxes, depreciation and amortization).
“Another beat and raise continues Bloom’s strong execution,” the analyst said.
Bloom’s sell-off is just part of a broader shift in investor sentiment, with even strong earnings struggling to lift tech stocks amid concerns over risks.
“For the last two weeks, investors have been sprinting from tech stocks and data center beneficiary stocks to safe stuff, and eventually, you run out of people willing to do that sprint, and that’s what today looks like and feels like,” Jed Ellerbroek, portfolio manager at Argent Capital Management, said in a CNBC interview.
Ellerbroek said strong earnings from tech companies could help ease investors’ fears.
“Emotion and fear play a really big role,” he said. But, “we’ve gotten a few tech companies’ [latest quarterly financial reports] and their earnings results have been good.”
Related: Cathie Wood sells $16 million of surging tech stock