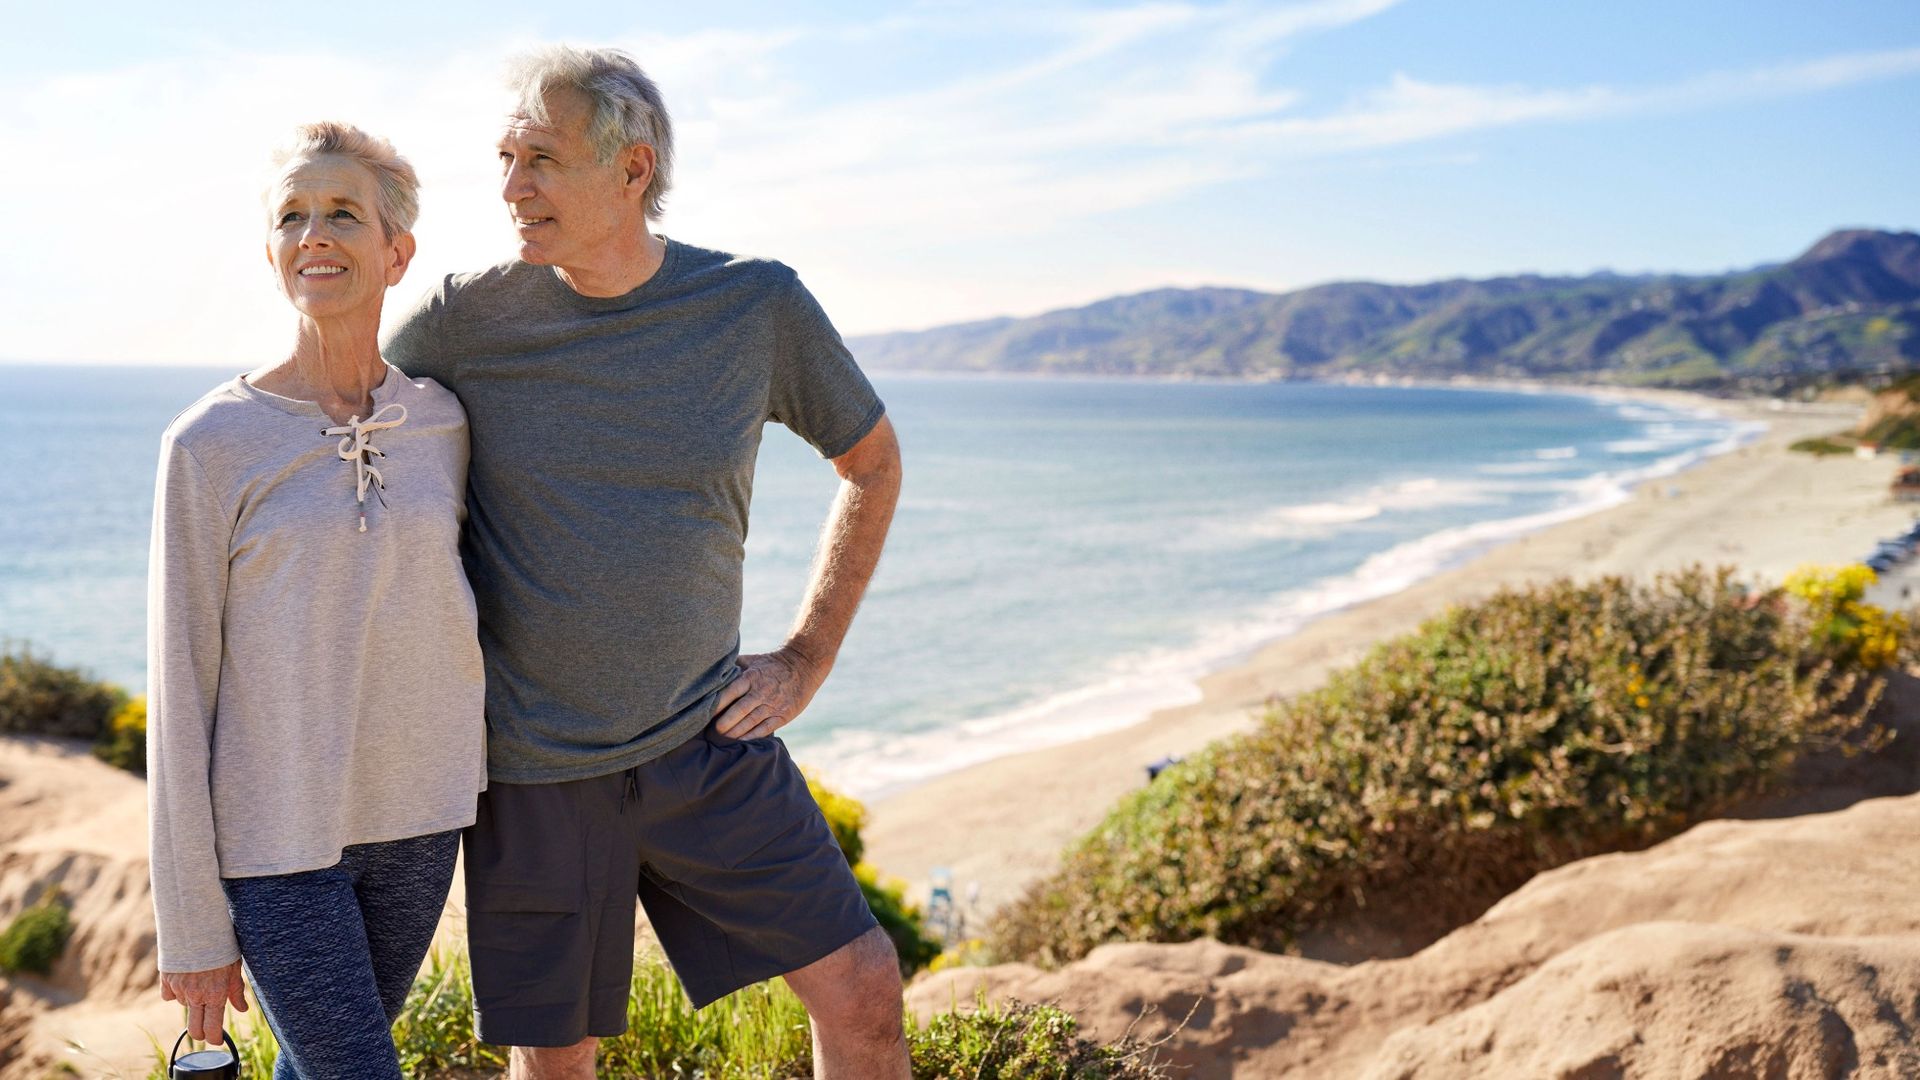
California can be a wonderful place to retire. The great weather, access to outdoor activities, good food and diverse culture are some reasons retirees choose the Golden State. That said, retiring there comes with its unique financial considerations. The cost of living is high, state taxes can take a big bite out of retirement income, and housing, transportation and healthcare costs can add up quickly. The overall cost of living in California is roughly 40% to 45% higher than the national average. Retiring comfortably in California requires careful planning and consideration. If you’re taking a do-it-yourself approach to retirement in California, here are a few areas to consider.Get a good handle on your expensesOne of the first steps in planning for retirement is understanding what it costs to maintain your lifestyle. This might sound obvious, but many of my clients come to work with me at Halbert Hargrove because I am a CFP® professional and wealth adviser. I review my clients’ bank and investment account information and help them analyze and understand how much they spend on a monthly or annual basis. While many of my clients know how much money they have in their bank accounts, they often don’t have a clear understanding of how much they spend on a regular basis. I recommend starting with your regular fixed expenses. Think housing, utilities, insurance, transportation and healthcare premiums. Then consider the expenses that don’t occur every month: Vacations, home repairs, property taxes or helping family are examples of some. Knowing your nondiscretionary expenses (what you need to spend), vs your discretionary expenses (what you want to spend), is helpful. If the stock market has a challenging year, knowing where you have the flexibility to cut back can help you adjust your withdrawals while you wait for the market to recover.About Adviser IntelThe author of this article is a participant in Kiplinger’s Adviser Intel program, a curated network of trusted financial professionals who share expert insights on wealth building and preservation. Contributors, including fiduciary financial planners, wealth managers, CEOs and attorneys, provide actionable advice about retirement planning, estate planning, tax strategies and more. Experts are invited to contribute and do not pay to be included, so you can trust their advice is honest and valuable.Plan for healthcare beyond MedicareCalifornia is home to some of the greatest medical institutions and hospitals in the nation including Cedars-Sinai Medical Center, Stanford Health Care, UC San Diego Health and UCLA Ronald Reagan Medical Center. But medical planning goes beyond finding the best doctors for the care you need.California retirees need to budget for Medicare premiums, Medigap or Medicare Advantage, Part D (prescriptions), dental, vision, long-term care and any out-of-pocket expenses. Knowing the average cost of healthcare as a starting point can help, but age, location and tobacco use can impact costs. There’s another issue: Higher taxable income can increase Medicare premiums through IRMAA (income-related monthly adjustment amount). This is a surcharge added to your monthly Medicare Part B and Part D premium if your income is above certain limits. What this means for retirees is a large IRA or 401(k) withdrawal might create a tax bill today and potentially higher Medicare premiums later.Pay attention to California taxesIn addition to a higher cost of living, California has one of the highest state income taxes in the U.S. State income taxes start at 1% and go up to 12.3%, plus an additional 1% for taxable income over $1M. This matters quite a bit when retirees are drawing from large IRAs, 401(k)s or pension plans, as the net distribution from a pretax account can be considerably lower after you account for taxes.Long-term capital gains tax, which is triggered by the profit you make from the sale of an asset held for more than a year, is also taxed in California using the same ordinary income rate that’s applied to withdrawals from pretax retirement accounts. At the federal level, long-term capital gains are taxed at a more preferential rate, so California is unfortunately unique in this regard. For retirees with substantial investment income, this can really increase their tax liability.One silver lining — California does not tax Social Security benefits, disability or survivor benefits, so retirees who live primarily on these types of income have less tax exposure.Don’t forget housing, property taxes and home insuranceFor many retirees, homes can make up a large portion of their net worth. This is especially true for California, where the prices of homes have skyrocketed throughout the years. I frequently hear my clients recount how they bought their first homes for tens of thousands of dollars, and have watched the property grow into a multimillion-dollar assets. A retiree in that situation might have substantial equity in their home, but a low-cost basis and property tax assessment. That can make a decision such as downsizing or moving to a retirement community much more complicated than simply looking at the price of the new home.Looking for expert tips to grow and preserve your wealth? Sign up for Adviser Intel, our free, twice-weekly newsletter.Before moving, consider the complete cost of the new property, including property taxes, homeowners’ insurance, homeowners’ association (HOA) dues and maintenance. A smaller or less expensive home might not lower monthly expenses by much, all things considered. When it comes to property taxes, keep in mind that Proposition 13 imposes a 1% cap on the tax rate and a 2% maximum for annual increases, offering some protection from long-term owners. If you’re a homeowner age 55 and older who wants to move from one California home to another, Proposition 19 allows you to transfer the lower assessed value of the primary residence to a newly constructed or replacement principal home. Eligible adults can use this tax transfer benefit up to three times.Keeping your California retirement on trackRetirement in California can be expensive, but for many people, the lifestyle is a significant factor in their decision to live here. Understanding the costs, staying flexible and recognizing how each financial decision affects others can help you make informed choices while enjoying this chapter of life. Related ContentCalifornia Retirement Tax 2026: Is the ‘Social Security Shield’ Enough?10 Cheapest Places To Live in California11 of the Best Places to Live in CaliforniaYour First 5 Potential Moves When Inherited Wealth Makes You Rich OvernightI’m a Financial Planner and a Parent: Here Are Five Money Habits Every Young Family Should HaveThis article was written by and presents the views of our contributing adviser, not the Kiplinger editorial staff. You can check adviser records with the SEC or with FINRA.
An Expert Guide to California Retirement Costs and Taxes