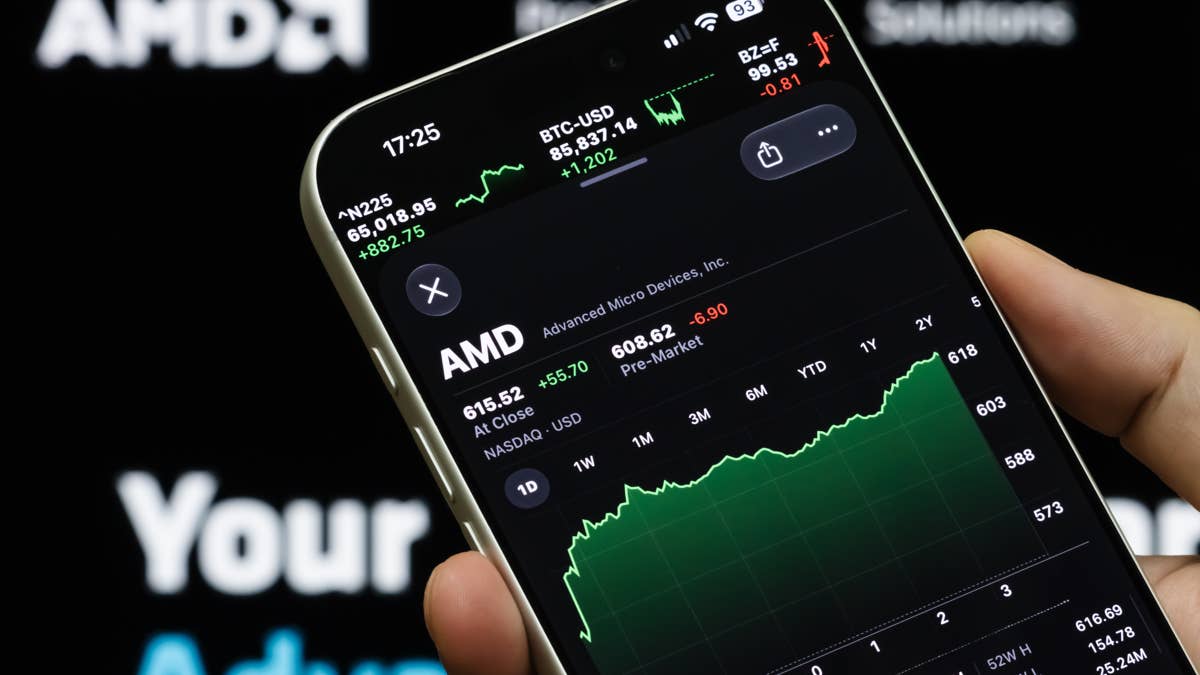
Here’s a strange pair of numbers. Bank of America just raised its AMD earnings forecast for 2027 and 2028. It also cut its price target by $70.
Both moves landed in a Nov. 3 research report seen by TheStreet, titled “Agentic Made Dependable: Growth Set to Accelerate Again in 2027.”
The higher estimates are about AMD’s business. The lower target is about the market. And buried in the risks section is a detail every AMD shareholder should understand.
AMD (AMD) gave the bank plenty to like. Third-quarter revenue rose 45% to $13.4 billion, and data center sales nearly doubled to $8.5 billion, the company said in its earnings release.
“We delivered a record quarter with revenue exceeding the high end of our guidance,” CEO Lisa Su said in the release.
Bank of America raised AMD’s 2027 and 2028 earnings estimates but cut its target to $650.Cheng Xin / Getty Images
Bank of America raised the forecasts and lowered the target
BofA analyst Vivek Arya kept his Buy rating and lifted his 2027 earnings estimate to $16.95 a share from $16.26. His 2028 estimate rose to $26.14 from $24.69.
AMD “checked every box we expected,” the note said. Fourth-quarter revenue guidance of about $17 billion beat the bank’s prior $16.15 billion forecast, and AMD raised its 2027 server CPU growth outlook to 100% from more than 70%.
The company now expects 2027 revenue growth above 80%, which the note says would be the fourth straight year of accelerating sales and earnings.
“AMD continues to execute quietly and consistently,” the note said.
Related: How much AMD stock does CEO Lisa Su actually own?
So why cut the target to $650? Chip stocks have gotten cheaper as a group. The bank now values AMD at 26 times 2028 earnings, down from 30 times.
Even after the cut, the target implies about 34% upside from AMD’s $483.90 close on Nov. 3. Shares jumped about 7% in premarket trading the next day, Tradingpedia reported.
The warrant math AMD shareholders should know
Two of AMD’s biggest AI deals came with a sweetener: the right for the customer to buy AMD stock.
OpenAI received a warrant for up to 160 million AMD shares in its 6-gigawatt GPU deal, The Fly reported. The shares vest in tranches as deployments scale.
Meta got the same size warrant in February, with an exercise price of 1 cent a share, Built In reported, citing The Wall Street Journal. Its final tranche depends on AMD’s stock reaching $600.
More on AMD:
AMD, Nvidia and Intel diverge as Morningstar resets the scorecard
Nvidia dominates AI chips, but BofA sees AMD closing in
5-star analyst resets AMD stock price target
Together, the warrants “could result in new issuance of 320mn shares, or ~20% of current share count through 2030, likely beginning in 2027,” the note said.
Here’s what that means, step by step, using the bank’s own 2030 model:
1. AMD could earn about $68.3 billion in 2030, Arya estimates.
2. Spread over 1.72 billion shares without the warrants, that’s about $39.70 a share, by my math.
3. Spread over the 2.04 billion shares the bank models with them, it’s about $33.50.
4. That gap works out to roughly 16% less profit per share for today’s owners.
At AMD’s Nov. 3 price, 320 million shares would be worth about $155 billion. That’s the cost of locking in two of the world’s biggest AI buyers.
To be fair, dilution only happens if the deals work. More shares would mean OpenAI and Meta are buying lots of AMD chips, and the bank already builds them into its $33-plus earnings power estimate.
What could still go wrong
The note lists the bear case plainly.
AMD’s key AI customers, including Meta and frontier labs, are buying from several chip vendors at once. AMD has to keep proving its chips deliver more output per dollar than Nvidia’s and custom chips from Broadcom and Marvell.
Valuation is another sticking point. AMD trades at 32 times expected earnings over the next 12 months, twice the multiple of Nvidia and Broadcom, the note said.
Rising memory costs could also squeeze margins, and PC and gaming sales face supply headwinds. Gaming revenue fell 40% in the third quarter, the company reported.
CFO Jean Hu struck a confident note. “Our fourth-quarter outlook reflects accelerating revenue and earnings growth,” she said in the release.
If you own AMD, I’d watch two numbers through 2027: data center revenue and share count. The first tells you whether the AI story is working. The second tells you how much of that success you actually get to keep.
Related: AMD CEO issues 2027 PC warning for stock investors