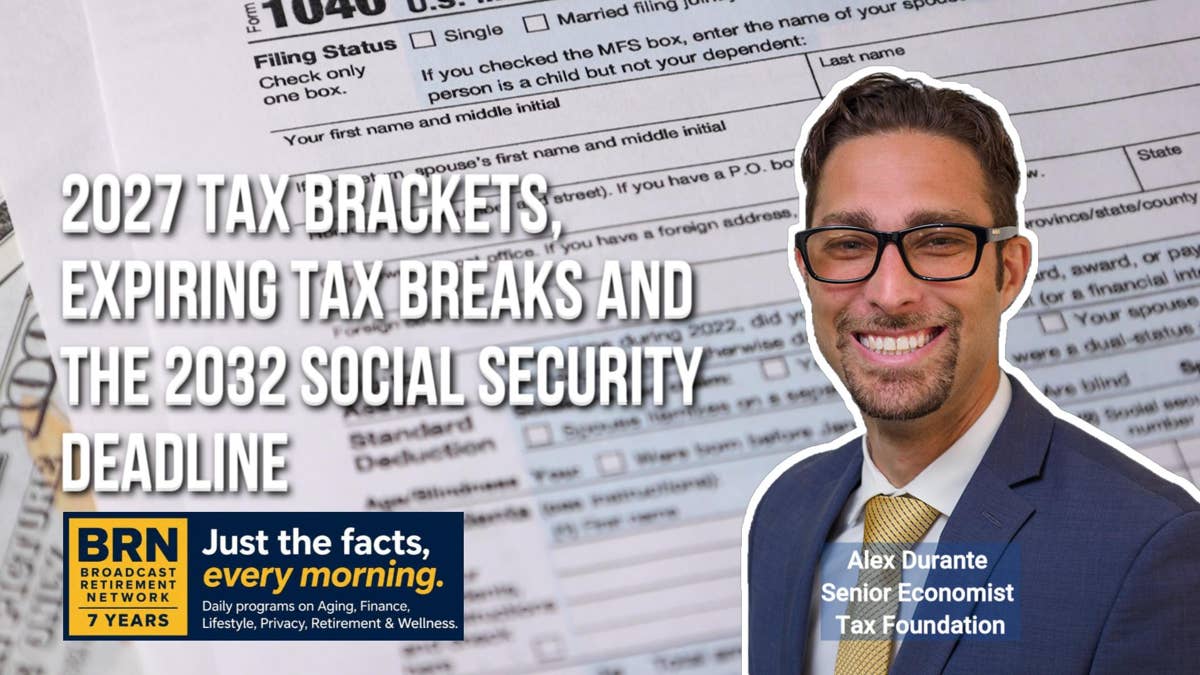
Alex Durante, Senior Economist at the Tax Foundation, explains the IRS’s 3.2% inflation adjustments to the 2027 tax brackets and what they mean for your tax bill.
Jeffrey Snyder, Broadcast Retirement Network
Alex, it’s so great to see you, thanks for popping by the program this morning.
Alex Durante, Senior Economist at the Tax Foundation
Hi, thanks for having me.
Jeffrey Snyder, Broadcast Retirement Network
Well, the pleasure is all ours, and I guess, I know you do a lot of work in economics and tax policy, hence the name of your organization, but let me ask you, your reaction to the bracket changes. We did a show earlier this month about the new 2027 bracket changes for income tax. I want to get your reaction as an economist, as someone who really works around policy, what did you take away from that?
Alex Durante, Senior Economist at the Tax Foundation
Yeah, so this is a pretty standard adjustment that the IRS makes every year. They’ve actually have been doing this since the early 80s, and the reason that they make these inflation adjustments is to avoid pushing people into higher brackets that happen if you have inflation. So before they adjusted the tax brackets for inflation, if workers were getting paid higher wages, just because there was, say, an upward inflationary spiral, which we had at the end of the 1970s, that would push them into higher tax brackets, even though they actually were not any wealthier.
So since the 1981 tax reform, these tax brackets have been adjusted for inflation each year, and this is something that sometimes folks get a little alarmed by, or maybe they don’t quite understand what it means, but that’s basically how it works. And for this year, the brackets are going to be adjusted upward based on an inflation rate of 3.2 percent, which is based on the preceding 12-month average that the IRS calculates. And the way I always like to frame this is that, ideally, what you would love to see is no inflation adjustment, because then that would actually mean that there was zero inflation in the economy.
So the fact that this has to be adjusted for 3.2 percent, which is above the Federal Reserve’s inflation target of 2 percent, I think also tells you something about the economy perhaps running a bit hot right now.
Jeffrey Snyder, Broadcast Retirement Network
So really good point. I was going to ask you about that, because obviously, or maybe not obvious to some, but I think obviously the rest of us, gasoline prices are up, although they have come down, food prices, other goods and services have come up. And I know that you said it’s backwards looking in that it’s been 12 months.
Is that still, given all the technological advancements that we have in the ability to calculate these things almost in real time, is that still, and I don’t want to put you, I’m not trying to put you in a corner. What I’m asking is, is it something that the Congress or administration, people in the federal government should look at and say, hey, maybe we should adjust that in a more favorable or less than 12 months, I guess.
Alex Durante, Senior Economist at the Tax Foundation
Yeah. I mean, this is a question I’ve been asked before. I mean, it is sort of, it is a lying indicator.
I mean, another way, I mean, they could do it, is they could just, they could have some kind of forecast that they use, but then you also risk either overshooting or undershooting. So it is, I mean, I could see, it is an imperfect measure. And as we know, I mean, the latest inflation report shows inflation actually around 4% right now.
So again, it’s unfortunately a lagging indicator, but I’m not aware of any alternatives, I think, that would perhaps improve the accuracy of it in a timely fashion.
Jeffrey Snyder, Broadcast Retirement Network
Yeah. And I guess, honestly, Congress and the federal government, they probably have other higher level priorities. I’m thinking like security and some of the other things.
Let me ask you about, if I may, if it’s okay, ask you about, what does this mean in terms of potential revenue? And I’m not asking for a specific, I’m like, this is not a place, of course, but does this mean that the government, the federal government could see an influx of even more revenue than it has in previous years, less revenue? Go ahead.
Alex Durante, Senior Economist at the Tax Foundation
Yeah. So the way I sort of frame this, because I’ve also been asked, and this is kind of related to your question, people will ask, well, does this mean, are folks going to get a tax cut? Are they going to get a tax?
Like, how do you think about this? And really determining whether you’re going to see your taxes go up or down next year really depend on a number of factors. So first of all, as I’m sure a lot of viewers are aware, there was a significant piece of tax legislation, the One Big Beautiful Bill Act that was passed in summer 2025, which made some of the tax provisions in the Tax Cuts and Jobs Act from 10 years ago that were scheduled to expire, made those adjustments permanent.
And then there were also additional measures of tax relief that were added. So one of these, as an example, was there was an additional standard deduction for seniors that was added to the tax bill. Now, that particular provision is scheduled to expire at the end of 2028.
And that particular measure itself is also not adjusted for inflation because it’s scheduled to expire. But let’s say perhaps you’re retiring this year, you might potentially qualify for that deduction and that would cause your taxable income to go down. But you can’t really determine what your tax liability is going to be just from looking at these inflation adjustments.
I mean, that’s going to be based on tax law and your own individual set of circumstances, whether you’re going to, say, claim the standard deduction or perhaps itemize your deductions, maybe you start a business this year and you have an additional source of income. So there’s a lot of factors that go into that. And you can’t look to these inflation adjustments to really tell you much about your tax liability, as well as the revenue that the government is going to bring in.
Jeffrey Snyder, Broadcast Retirement Network
You know, in terms of, you know, we have a new Congress coming in in January, party switch in both houses, Senate and in the Congress. I would imagine that tax reform, I mean, it’s only two years till we have the 2028 presidential elections. And again, ours is not a political show.
But would you imagine that this is something that you mentioned 2028 in terms of perhaps the permanence of that one tax provision? Would you think that there’d be other things that may come up? I guess, do you think that that would be an agenda item?
Alex Durante, Senior Economist at the Tax Foundation
Right. So the additional senior deduction, as well as the deduction for overtime income, the deduction for tipped income, the deduction for all the loan interest, all of those provisions are scheduled to expire at the end of 2028. And I think what we are likely to see is that a lot, I imagine those will mostly be extended, maybe they scale back.
So maybe instead of allowing you to deduct up to, I think for tips, it’s maybe $20,000 in tipped income. Maybe they claw that back to only $10,000. But the issue is that if you look at, I mean, as an example, that particular provision, the deduction for tipped income, that passed as a separate standalone bill to Senate 100 to zero before they even took up this One Big Beautiful Bill Act.
So there was a lot of bipartisan support to do legislation like that. And while, of course, tipped employees benefit and they like it, that does mean that there’s less revenue going to the government, there’s less revenue available for perhaps other kinds of spending priorities that Congress might have. And I think we really do have to take a careful look at a lot of these provisions and think about, well, what actually works best for the government and the economy as a whole, rather than looking to give benefits to particular groups and particular individuals throughout the tax code.
Jeffrey Snyder, Broadcast Retirement Network
And also to that end, I want to ask you about the federal deficit. I mean, I think the number is exorbitant. I don’t even know what it is as of today.
I think it goes up like significantly every, they have a clock that calculates the national, in any event, I would expect that number to continue to grow. These tax receipts, even if they were to receive money, is that enough to kind of cut into that deficit? Because I know, you know, I like to manage my own debt.
Alex Durante, Senior Economist at the Tax Foundation
So, yeah, so the way to think about this is that the two largest contributors to the debt and deficit deficits that we have are the mandatory spending program, Social Security, Medicare. And what I mean by, when I say mandatory, like by law, those payments have to go out regardless of whatever else the government decides to do with the discretionary budget. So even if the government said, we’re not going to spend $1 more on a discretionary budget, which includes, say, military expenditures and includes all different, various kinds of welfare assistance, subsidies, all kinds of other government spending.
Even if they said, we’re not going to spend $1 more on any of that because of Social Security and Medicare, the spending will continue to go up. And actually, since we broached the subject here of perhaps 2028 of an ex-Congress, I think what viewers really need to be aware of is that the Social Security Trust Fund is scheduled to expire at the end of 2032, which means that if, when the Social Security Trust Fund is depleted, under current law, there would be an immediate 22% reduction in benefits unless Congress passes legislation to fix that.
The reason I highlight this is that the senators that were just elected a couple of weeks ago, those are going to be the senators that are going to be here when this crisis comes in the past. And they’re going to be the ones that are tasked with fixing that. So I think in the context of this conversation, they have to think about not just what those programs look like or what Social Security looks like at the end of 2032, but also think about other ways the government can potentially raise revenue to address that.
Or they’ll have to look to trim the benefits or perhaps raise retirement age, as we did in 1983 when we faced similar headwinds.
Jeffrey Snyder, Broadcast Retirement Network
Yeah, I mean, this is not a, it’s not like no one knew this was coming, right? I mean, they’ve dealt with it before. We just have a very big demographic shift in this country with a lot of us, myself included, getting to be older and needing help and living longer.
I mean, it is just a fundamental change in our society. And so do you think, and again, you can punt on this, you don’t tell me, but do you think that this is something that they’ll have to take up? Because 2032 is only a few years, not a few, but it’s several years away.
But you can’t just make the change six months in advance.
Alex Durante, Senior Economist at the Tax Foundation
I mean, I guess- No, that’s right. Well, I mean, there’s a couple of things they could do. I mean, they could, before, this is actually similar to what happened in 1983, where they basically realized that Social Security trust fund was depleting.
And then like six months before it happened, Congress got together and passed a series of reforms. Now, some of those address the immediate deficit and the trust fund, but others get phased in over time to address projected deficits beyond that window. So for instance, in 1983, the payroll tax itself had a phased in increase that I believe was fully phased in by 1990.
I mean, since then it has not been adjusted. And similar things happened with the retirement age, where there was actually a phased in increase from that law that went into effect, I think, a few years ago. And I think that’s something similar that we’re going to see likely happen with Congress, because they’re not going to want to concentrate all of the pain of this adjustment on one generation, because it’s just politically not viable.
So I imagine they’ll look to do something along those lines of phased in reforms over time. And again, this is not just, and we don’t just have the US experience to look to for this, but other countries that faced similar crises in their retirement programs in the 80s and 90s. I mean, this is basically the approach that they took.
So we do have precedent for it. But again, I would say I am not especially optimistic that Congress is going to do anything on this until they absolutely have to in 2032. So I don’t think it’s going to be on the agenda for senators in 2020.
I think it should be, because this is a really important issue, but I think it’s unlikely.
Jeffrey Snyder, Broadcast Retirement Network
Well, I guess it’s up to us, right, to hold people accountable, meaning not you and I. I’m talking about the 330 million or whoever, whatever percentage of people that are voting, that are voting age eligible. It’s their job to hold their senators and congresspersons and elected officials accountable.
I guess we’ll see. I think it’s interesting. It’s a conundrum, as you said, that not only the US has faced, but others are facing.
China, you look around the world. Everyone’s getting older and they’re having to true this up. Alex, we’re going to have to leave it there.
Thank you so much for the conversation. And look, we look forward to having you back on the program again very soon.
Alex Durante, Senior Economist at the Tax Foundation
Great. Thank you.